
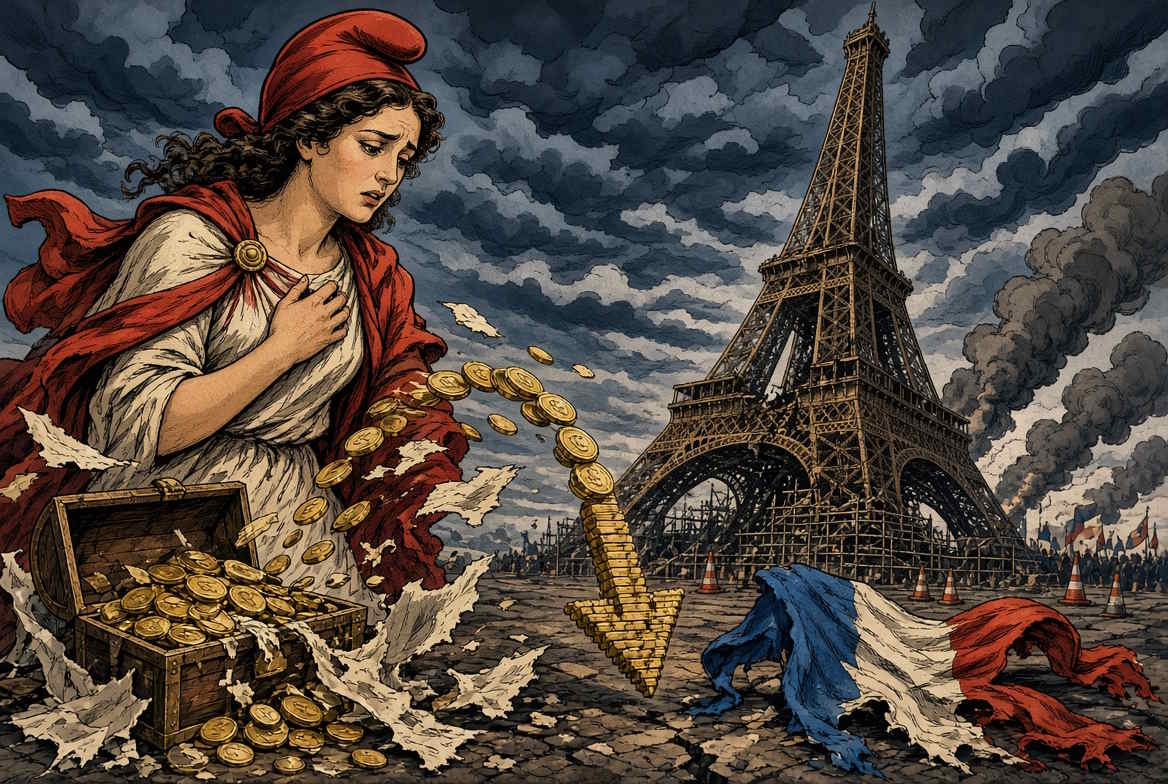
France is at risk of becoming the epicenter of the next Eurozone crisis. Yields on French government bonds are at their highest levels since 2002, investor confidence is waning, and Paris lacks the political will to implement necessary reforms. Nevertheless, the ECB should not rush to the country’s aid.
The country is faltering both politically and economically. Student protests are escalating into street battles, fishermen are blockading roads over fuel prices, and public sector workers are demanding more pay for less work. In France, uprising is less an exception than a national ritual: those who are dissatisfied set things on fire and call it democracy. This civil unrest is colliding with an already tense market situation.
The debt-to-GDP ratio is heading toward 120 percent. This places France third in the Eurozone—behind Greece and Italy—with a ratio nearly double that of Germany. It is an embarrassing situation for a nation that likes to portray itself as a leading power and a moral authority in Europe, yet cannot even get its own budget under control. The spread between French and German bond yields has climbed to 1.4 percentage points—a wider gap than that of Italy, Greece, or Spain. Investors are demanding a substantial risk premium, and the euro has already lost ground against the dollar and the Swiss franc. What passes for greatness in Paris looks like a major concentration risk for the entire currency union in the eyes of the markets.
Observers are already speculating whether the ECB might activate its TPI bond-buying program—created in 2022—for France for the first time. The conditions for its use are defined loosely enough that deploying it could easily be justified. Milder options are being considered first: downplaying the inflation rate—which jumped to 3.8 percent in September—in order to delay interest rate hikes; verbally intervening in favor of French bonds; or strategically reallocating maturing funds from the PEPP pandemic program to Paris. All of this would merely reward the lack of willingness to enact reforms.
Prime Minister Sébastien Lecornu lacks a parliamentary majority, and the opposition refuses to support unpopular austerity measures ahead of the 2027 presidential election. The French crisis thus carries a genuine risk of escalation. That is precisely why the ECB should hold back. Those unwilling to solve their own problems should not be allowed to offload them onto their neighbors. France must foot its own bill rather than treating the Eurozone as a convenient insurance policy against its own incompetence.
 Source: internet24 Boulevard

Leave a Reply